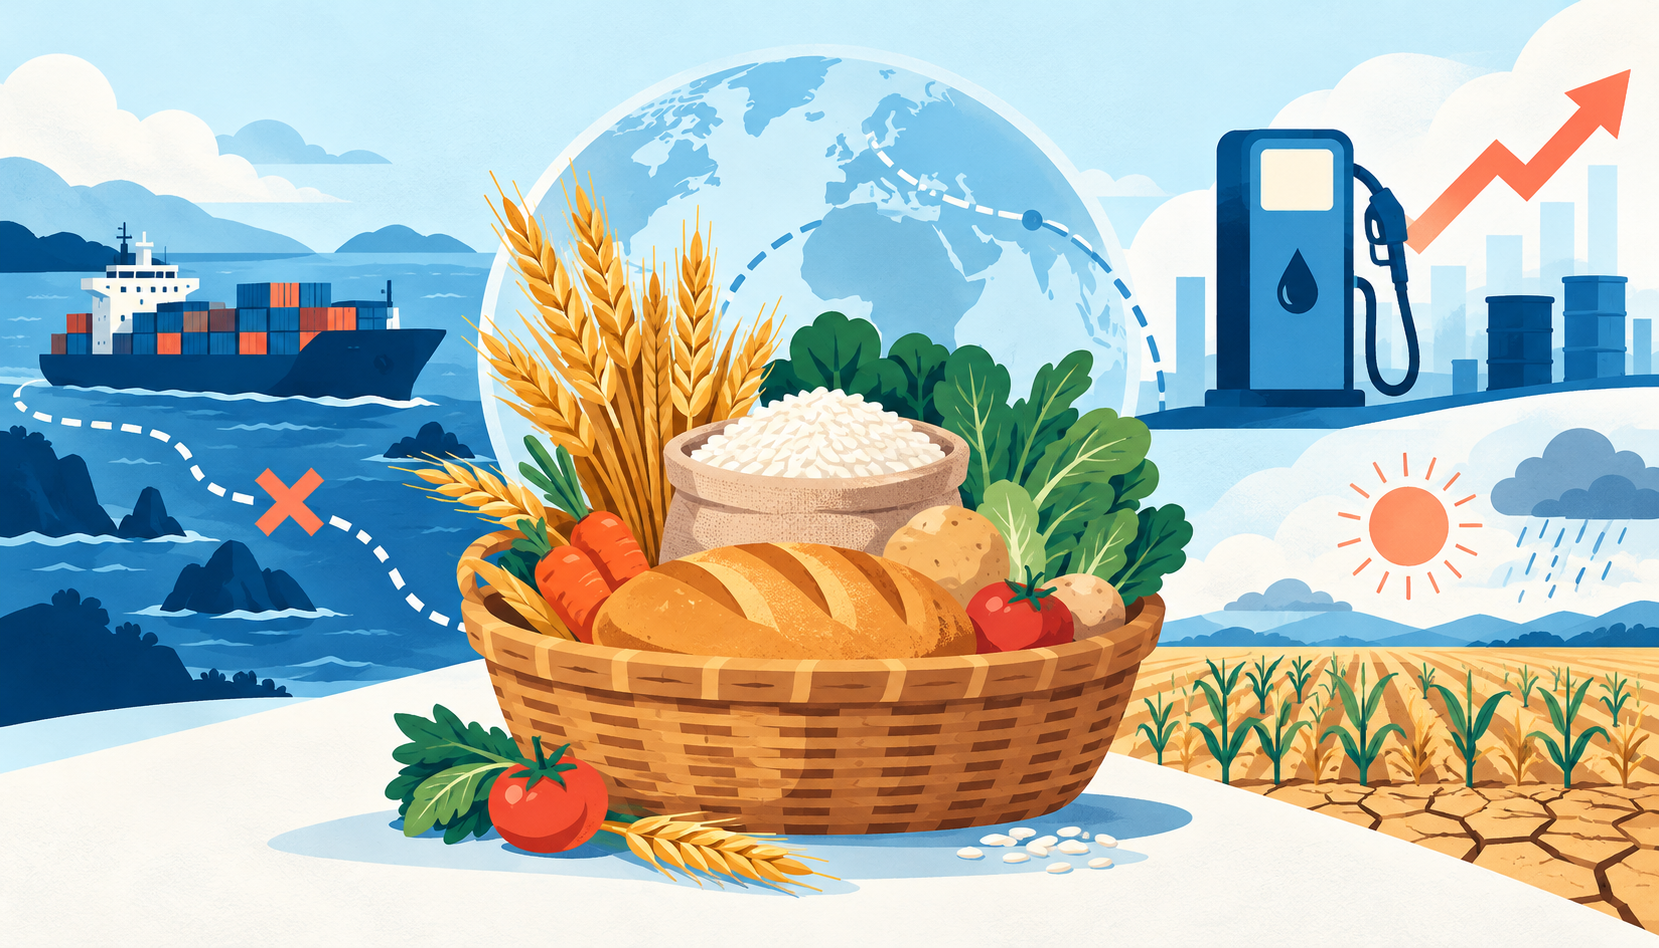
Global food inflation faces renewed upward pressure as shipping disruptions, higher energy costs, and adverse weather squeeze the availability of key staples. The latest official data show international food prices rising, while climate forecasts point to continuing production risks. The extent of any further increase in household food bills will depend on exchange rates, domestic harvests, government policy, and how long the disruptions last.
The UN Food and Agriculture Organization’s September price release, published on October 2, put its global food commodity index at 136.0 points, up 1.5 percent from August and 5.8 percent from a year earlier. FAO Chief Economist Maximo Torero warned that sustained pressure on energy, transport, and agricultural commodities could feed through to consumer food prices, especially in import-dependent countries.
That is a conditional warning. Commodity quotations measure an earlier stage of the supply chain than supermarket prices. Yet the combination of expensive imports and disrupted transport creates a difficult outlook for households whose budgets already leave little room for a more costly diet.
Crop prices show the strongest pressure
FAO’s Food Price Index tracks internationally traded food commodities across five groups. Its September figures show a mixed picture: cereals rose 5.1 percent from August, sugar increased 6.1 percent, and vegetable oils gained 0.9 percent. Meat prices fell 1.1 percent, while dairy prices edged down 0.1 percent.
The difference between categories matters for businesses. A bakery buying wheat, a confectionery manufacturer buying sugar, and a meat processor face different input costs. Even within one country, retail inflation can vary according to the mix of imported products and locally produced food that households consume.
Substitution can cushion some of the pressure. Consumers may switch foods, and producers may change recipes or animal-feed mixes. Those adjustments have limits when several staples become more expensive together. A cheaper alternative also offers little protection if it is unavailable locally or requires cooking fuel that has become more costly.
For businesses, the challenge is managing the interval between paying for inputs and receiving cash from customers. Higher replacement costs can consume working capital before a company reports a large change in its profit margin. Small processors and distributors with thin cash buffers may feel that strain sooner than larger firms with longer supplier terms.
Adequate global harvests can coexist with tight trade
FAO’s October Cereal Supply and Demand Brief forecasts global cereal production of 2,979 million tonnes in 2026. That would be 2.1 percent below the previous year’s record but still the second-largest harvest recorded. The agency forecasts cereal stocks of 950 million tonnes at the close of seasons in 2027 and a stocks-to-use ratio of 31.7 percent, compared with 32.0 percent in the previous season.
The trade outlook is less comfortable. FAO projects cereal trade of 505.8 million tonnes in 2026/27, down 3.5 percent from the previous season. Its October revision reflects constraints on Black Sea shipping and insufficient alternative transport capacity affecting wheat and maize exports.
These figures argue against treating the situation as a uniform global shortage. Food can exist in storage or in a producing region while remaining expensive to deliver to an importing country. The practical constraint may be a port, vessel, rail connection, insurance policy, or access to foreign currency.
Importers therefore need to examine the location and availability of stocks alongside the global total. A reserve held far from an established trading route may offer less immediate relief than a smaller volume available through a functioning port. Buyers able to diversify origins and delivery dates may have more flexibility, although changing suppliers can raise costs and require new quality checks.
Energy and freight add a second cost shock
The World Bank’s October commodity update, covering September, reported a 25.7 percent increase in its energy price index. Crude oil rose 21.2 percent and natural gas 15.3 percent. Its food price measure increased 3.8 percent and fertilizer prices edged up 0.4 percent during the month. The Bank’s food index and FAO’s index use different baskets, so their percentage changes should be read separately.
Energy affects food costs through several routes. Farmers need fuel for machinery and transport; irrigation and cold storage need power; fertilizer production depends on energy inputs. Processors then pay to mill, bake, package, refrigerate, and distribute food. An energy shock can reach consumers even when the farm-gate price of a particular crop changes little.
Freight disruption creates another expense. Longer routes can tie up vessels and inventory, while uncertainty encourages buyers to carry more stock. Companies may have to finance larger shipments or pay earlier to secure supply. These costs can persist after headline commodity prices stabilize because contracts and inventory turn over gradually.
The reverse is also possible. Improved shipping access, cheaper energy, or a stronger local currency could slow retail price increases. A responsible outlook needs to track those potential offsets alongside the risks.
Climate forecasts extend uncertainty over the next harvest
The World Meteorological Organization’s October seasonal update projects a further strengthening of El Niño during October to December, with Pacific warming expected to peak around December. Its earlier September El Niño update placed the likelihood of persistence through February 2027 near 100 percent.
These are climate forecasts, rather than crop-loss estimates. The effects will depend on regional rainfall, planting dates, irrigation, and the stage at which crops experience heat or water stress. The same global climate pattern can produce dry conditions in one area and excessive rain in another.
The timing creates a planning problem for governments and lenders. A country may be importing food at higher prices while farmers need financing for the next season. Cutting fertilizer or delaying planting to save cash could weaken later output. Financing additional inputs also carries risk if local weather prevents a viable harvest.
Seasonal forecasts are most useful when combined with local crop assessments and water conditions. Updating procurement and lending assumptions as that evidence changes is more useful than assigning one global loss estimate to every agricultural borrower.
The domestic impact will differ sharply
The World Bank’s September Food Security Update, using data available as of September 16, described generally adequate global supplies alongside rising commodity prices. It reported food inflation above 5 percent in a large share of low- and lower-middle-income countries and acute pressures across several regions, including Eastern and Southern Africa, the Middle East and North Africa, and South and Central Asia.
That publication predates the latest monthly commodity data. It establishes an existing vulnerability rather than measuring October conditions. National consumer-price releases will be needed to determine how much of the recent international increase has reached households.
Exchange rates can widen the differences between countries. An importer paying in dollars may face a higher local-currency bill when its currency weakens, even if the export price holds steady. A stronger currency, a good local harvest, or the release of usable reserves could soften the impact elsewhere.
Governments face competing pressures. Subsidies and lower import duties can help consumers, but they can also reduce revenue or raise spending when borrowing costs are high. Targeted support can limit the fiscal bill, although its effectiveness depends on identifying and reaching vulnerable households. Broad price controls may provide short-term relief while making it harder for suppliers to cover replacement costs.
Monetary policy faces a related trade-off. Interest rates cannot reopen a shipping route or produce rainfall. Central banks still need to assess whether food-price increases are spreading into wages, services, and expectations. The policy response will depend on those wider effects and the strength of domestic demand.
Analyst’s View
For credit risk, the first priority is the cash conversion cycle. Food importers and processors should be assessed against higher inventory costs, longer delivery times, currency movements, and the speed at which they can adjust selling prices. A company with stable sales volumes can still face a funding gap if each shipment requires more cash and arrives later.
For sovereign risk, food and energy exposure should be considered together. Countries importing both may face simultaneous pressure on foreign-exchange reserves, subsidies, and household purchasing power. Analysts should examine reserve availability, procurement obligations, financing access, and the budget cost of existing support schemes before assuming that a temporary price shock will remain manageable.
For market positioning, the key distinction is between exposure to rising prices and the capacity to earn from them. Producers may receive higher selling prices while also paying more for energy, fertilizer, and finance. Retailers may defend revenue while losing margin. The strongest balance sheets will have room to fund inventory, diversify suppliers, and absorb a period of weaker demand.
The next evidence to watch is concrete: shipping access, crop assessments, exchange rates, national food-price releases, and changes in emergency support. Current official data support the risk of further food inflation. They do not establish a common retail-price path for every country or a fixed timetable for relief.